Krispy Kreme shares have beaten NVIDIA over the past year, an improbable market comparison spreading across social media as investors reassess artificial-intelligence spending. A November 6 Polymarket post, amplified by Michael Luo, drew attention to the doughnut chain’s gain. The claim concerns stock-price returns, not computing performance, revenue growth or company size.
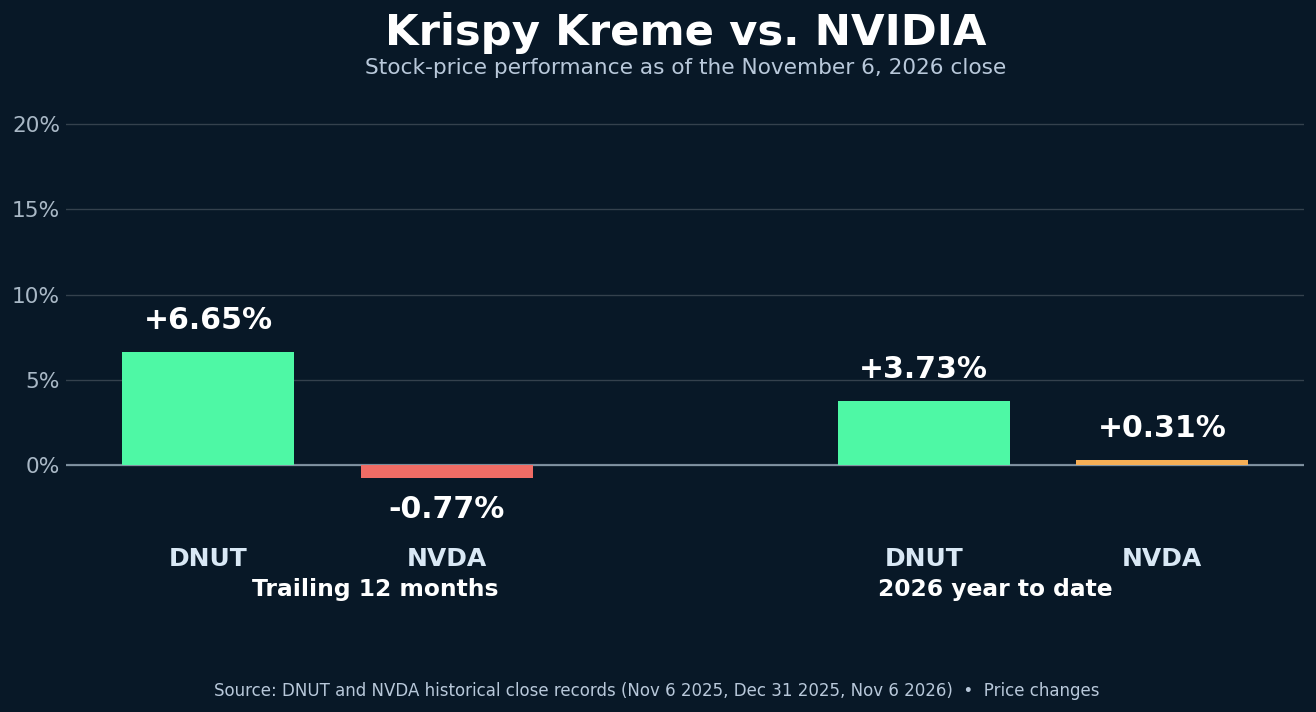
Using November 6, 2026 closing prices and the corresponding historical benchmarks, Krispy Kreme (NASDAQ: DNUT) gained 6.65% over one year, while NVIDIA (NASDAQ: NVDA) lost 0.77%. Since December 31, 2025, DNUT gained 3.73% against NVDA’s 0.31%. Returns are calculated from share prices without dividends, and change with the selected dates.
A doughnut earnings jump meets an AI-stock selloff
Krispy Kreme jumped 30.68% on November 5 to $4.60 after releasing third-quarter results. The gain partially reversed on November 6, when shares closed at $4.17, down 9.35% for the session. NVIDIA fell 9.26% on November 5 and rebounded 2.78% on November 6, closing at $186.64. The rapid swings show how one market snapshot can exaggerate a durable investment advantage.
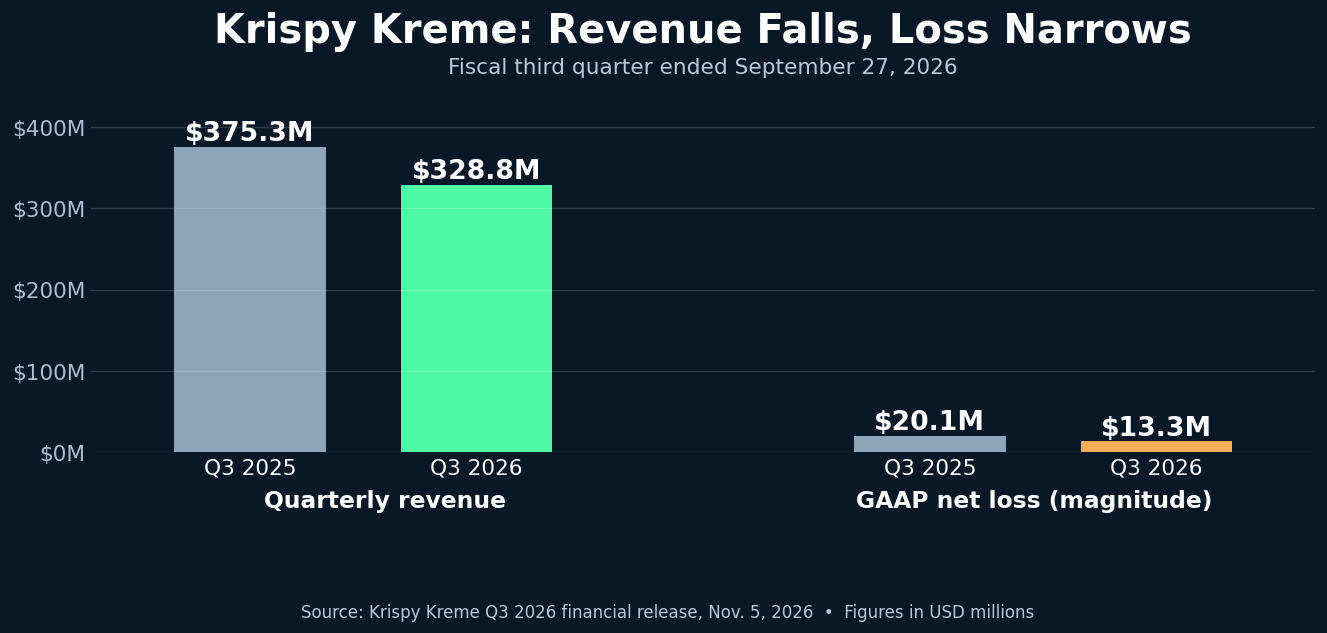
Krispy Kreme’s November 5 earnings release reported $328.8 million in quarterly revenue, down 12.4% from $375.3 million a year earlier. Its GAAP net loss narrowed to $13.3 million from $20.1 million. The company attributed lower reported sales primarily to franchising transactions, while systemwide sales rose 1% in constant currency.
Management raised and narrowed projected full-year revenue to $1.35 billion–$1.40 billion, up from an earlier $1.25 billion–$1.35 billion range. Adjusted EBITDA of $35.3 million declined 13.1% versus the prior quarter-year comparison; excluding a $9.3 million cybersecurity insurance recovery recognized in the year-earlier quarter, the company calculated a 12.7% increase. The non-GAAP adjustment matters when judging its turnaround.
NVIDIA’s business remains much larger
NVIDIA’s latest published quarterly report tells a very different operational story. The AI-chip company reported $96.2 billion of revenue for its fiscal second quarter ended July 26, 2026, up 106% year over year. Data Center revenue reached $89 billion, up 117%, according to NVIDIA’s August 26 announcement. Strong earnings growth can coexist with a falling stock price when valuations and expectations reset.
BitcoinVersus.Tech has separately followed the AI-chip market selloff, the wider semiconductor sales cycle, NVIDIA-linked 800-volt data-center rack designs, and AI inference acceleration. Each development highlights technological investment far removed from doughnut retailing.
Neither percentage-return comparison establishes a superior company or a forecast. Krispy Kreme carries the risks of a smaller business, lower reported revenue and continuing net losses. NVIDIA faces expectations surrounding infrastructure demand, capital spending, export restrictions and GPU competition. The verified takeaway is narrower: during the chosen trading windows, an ordinary consumer stock outpaced a dominant AI supplier.
Editor’s Note: Price changes were independently calculated from the November 6, 2025 and December 31, 2025 benchmark closes and November 6, 2026 closes, using DNUT trading records, NVDA historical prices, and DNUT’s November 6 closing quote. Company financial figures were checked against Krispy Kreme’s earnings release and NVIDIA’s results. The featured image is editorial artwork, not a trading screenshot. Social-post rendering and mobile display require live verification.

To donate 5,000 sats, open the article on a separate display and scan the original QR code with a compatible Bitcoin wallet. On mobile, use another screen or your wallet’s supported image-scanning feature. Verify the destination 3C9o19EH5HSiwEPyCTmEKzxhNCbo2X6TTb before sending.
We volunteer daily to ensure the information on this platform is Verifiably True. If you would like to support the research, please scan QR code.
BitcoinVersus.tech is not a financial advisor. Financial and energy-market coverage is provided for informational purposes.


Leave a Reply